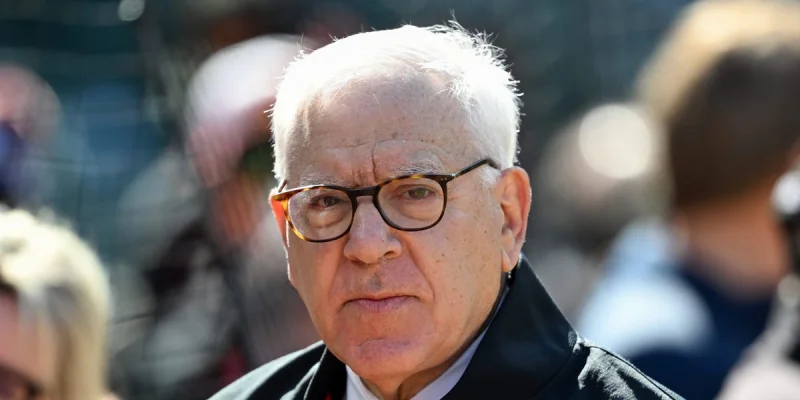
David Rubenstein said he bought the Baltimore Orioles for around $1.7 billion in 2024 because he wanted to “try to do something for the city.” He paired that civic explanation with a blunt account of his worst investing mistakes: walking away from Facebook and Amazon at the beginning.
The purchase gave Baltimore a new owner with a public philanthropic rationale, not just a financial one. For investors, Rubenstein’s comments also offered a rare window into how a private-equity billionaire weighs missed early bets against today’s AI boom.
Orioles buy and Baltimore motive
$1.7 billion is the price Rubenstein said he paid for the Baltimore Orioles, and he tied the deal to his hometown by saying he had not done much on the philanthropy front for Baltimore. His comment points to a purchase framed as a civic act as much as an ownership change, with the team now sitting at the center of a broader question about how wealthy buyers justify major sports acquisitions.
2024 is when the deal closed, and Rubenstein’s own explanation was simple: he wanted to “try to do something for the city.” That puts the transaction in a different category from a pure investment play, especially for a buyer whose fortune came from finance rather than sports operations.
Facebook and Amazon mistakes
Many billions of dollars is the value Rubenstein said was left on the table when he and his partners sold their Amazon stake after the stock collapsed during the dot-com bubble. He said Jeff Bezos gave Carlyle a stake at the very beginning, then the position was dumped after the collapse, turning a small early allocation into what would have been a vastly larger sum today.
$30,000 was the amount Mark Zuckerberg was trying to raise when Rubenstein said his then-future son-in-law asked him to invest. Rubenstein said, “I didn’t take it seriously,” and Eduardo Saverin ended up providing the initial capital instead. He described his gravest investing error as “walking away from Facebook and Amazon at the beginning.”
AI valuations and Nvidia
“Really, really high” was Rubenstein’s description of AI company valuations, and he said some are hard to justify with earnings. He pointed to Nvidia’s recent blockbuster results as evidence that the story is not “all pie in the sky,” but he also said not every AI company will survive and make money.
“As we learned in the dot-com era, not every dot-com company survived and made money, and not every AI company will survive and make money,” he said. The comparison matters because he is not dismissing the whole theme; he is warning that a strong category can still leave weak companies behind, especially when investors start treating every AI name as interchangeable.
What Rubenstein says to hold
Rubenstein also acknowledged concerns about aggressive accounting, circular financing, hidden debt, and overinvestment in AI. He quoted Warren Buffett saying that “when the tide goes out, we’ll see who’s been swimming without a bathing suit,” then added that the biggest mistake people make when bubbles burst is selling everything and getting out.
Markets have historically rebounded after crashes, he said, and “probably that’s the time to hold on and maybe buy more.” The sharper question now is how much of the Orioles purchase was a philanthropic decision versus a financial investment, because Rubenstein’s own framing suggests he was already thinking beyond the scoreboard when he wrote the check.