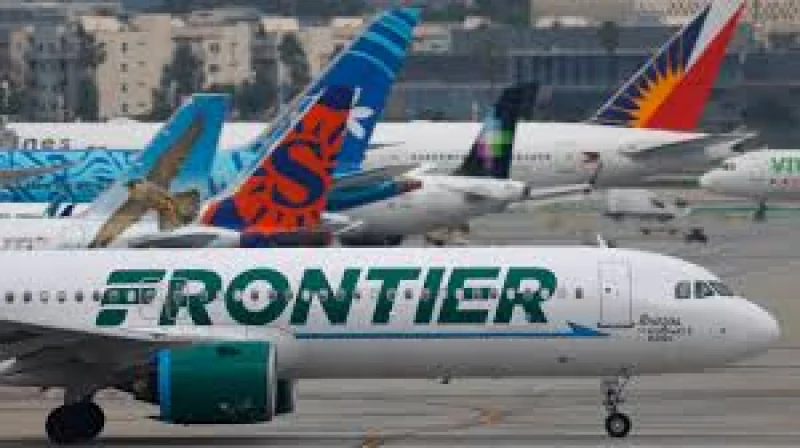
Frontier Airlines passenger fare increase Q3 showed up in Frontier Group Holdings' third-quarter 2026 results, where passenger revenue rose 55.4% year over year to $1.33 billion and total revenue reached $1.36 billion. Investors in Frontier Group Holdings got a cleaner read on pricing power and volume, but the quarter also carried a mixed operating message.
EPS of $0.18 added to that picture after a year-earlier quarter in which EPS was -$0.34. The shift gives investors a clear earnings rebound to weigh against the carrier's operating metrics, which show that revenue growth did not come with perfect execution across every measure.
Frontier Group Holdings' $1.36 billion quarter
$1.36 billion in revenue marked a 52.9% increase from the quarter ended September 2025. That is the headline change in the period: the company expanded both its top line and its passenger revenue base at a pace that signals a much stronger quarter than a year ago.
$1.33 billion in passenger revenue accounted for almost all of the company's reported revenue and climbed 55.4% year over year. In plain terms, the quarter was driven by more money per passenger-related sale, not just by a larger reported total.
Frontier Group's operating mix
78.8% load factor and 9 billion revenue passenger miles show the quarter's traffic profile, while 11.42 billion available seat miles set the capacity base. The comparison matters because passenger revenue gains normally have to clear both demand and supply conditions at the same time, and this quarter's reported figures show a business carrying a larger sales load across a larger network base.
11.87 cents total revenue per available seat mile, 7.84 cents adjusted CASM excluding fuel, 11.56 cents adjusted CASM, and 11.52 cents adjusted CASM plus net interest give the cost-and-yield frame investors use to judge whether the revenue jump was earned efficiently. Fuel cost per gallon came in at $3.96, average stage length was 891.00 miles, and fuel gallons consumed reached 107.21 million, all of which feed into the quarterly cost structure without changing the basic fact that revenue rose faster than the headline traffic metrics alone would suggest.
ULCC investors weigh the gap
Wall Street was watching the quarter against the Zacks Consensus Estimate and analyst averages, and the reported numbers were strongest where it counts most: revenue and EPS. The complication is that the operating picture was not clean across every metric, with load factor and revenue passenger miles below analyst estimates even as passenger revenue and earnings moved higher.
That split leaves Investors in Frontier Group Holdings with a straightforward next question: whether the passenger revenue surge reflects a durable fare improvement or a one-quarter step-up tied to the latest operating mix. The answer matters because the quarter ended September 2026 now sets the benchmark for the next print, and any follow-through will have to show up again in revenue, load factor, and unit-cost measures rather than in passenger revenue alone.