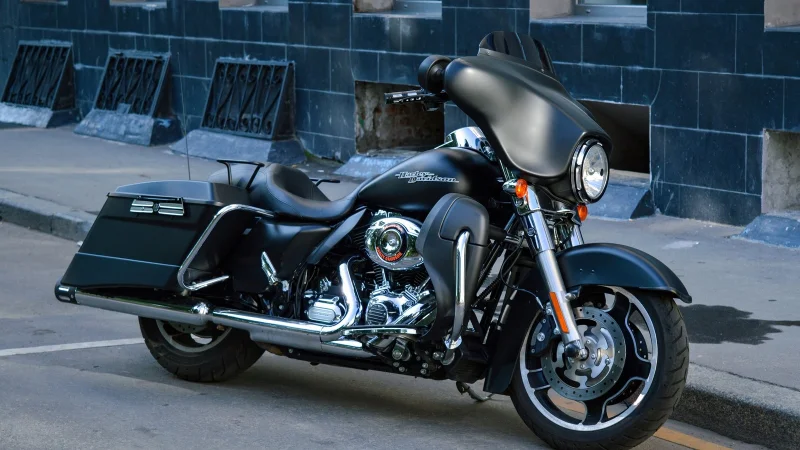
Harley-Davidson stock climbed to US$31.22 after a 27.17% 30-day gain and a 51.26% year-to-date rise, even as third-quarter profits and margins fell sharply from a year earlier. For investors in Harley, that leaves a stock price above the $29.80 fair value estimate while the latest results point in the opposite direction.
US$31.22 after a 27.17% run
US$31.22 is the latest close, and it comes after a stretch that lifted the shares 27.17% in 30 days and 51.26% so far this year. That move has put Harley-Davidson back in focus even though the company’s third-quarter profit picture weakened, turning the stock itself into the main story.
51.26% year to date is strong enough to change how the market frames the name, but the gain is not happening in a vacuum. Harley-Davidson’s most followed narrative puts fair value at $29.80, which leaves the latest close about $1.42 higher than that estimate, a gap of roughly 4.8%.
Third-quarter profits fell sharply
Lower third-quarter profits and margins were the main drag in the latest operating update. Harley-Davidson still posted healthier global and North American motorcycle unit volumes, so the business is not running on weak demand alone; the issue is that volume and profitability are not moving together.
19.02% 1-year total shareholder return shows the stock has still delivered a positive twelve-month result, but the 5-year total shareholder return decline of 7.85% keeps the longer record muted. That split matters because the recent rally is being judged against a base that was not especially strong for a stock with uneven multiyear performance.
Back to the Bricks in 2027
US$150 million is the cost-savings goal tied to the Back to the Bricks cost program by 2027, alongside HDMC EBITDA of US$350 million or more. The program is described as on track or slightly ahead after early headcount and cost of goods actions, which gives the rally a concrete operating target instead of just a price move.
Whether Harley-Davidson can sustain the recent gain depends on whether tariff costs stay manageable and whether a tilt toward more affordable models avoids squeezing margins further. Investors in Harley now have a simple test: the stock has already outrun the fair value estimate, so the next leg has to come from execution, not just momentum.